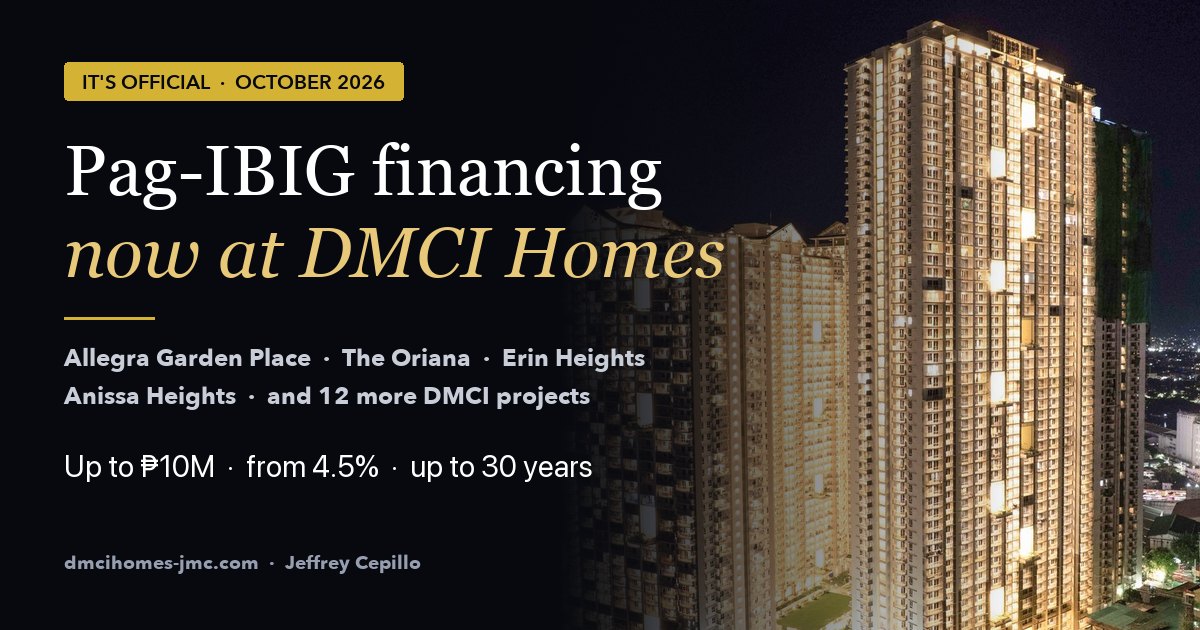
DMCI Homes now accepts Pag-IBIG Fund housing loans for the balance on the 16 projects on its official list, including Allegra Garden Place (Pasig), The Oriana and The Erin Heights (Quezon City) and Anissa Heights (Pasay). On those projects it joins spot cash, bank financing and DMCI in-house financing.
Pag-IBIG lends up to ₱10 million for up to 30 years. Until December 31, 2026 it is running promotional rates of 4.5% on loans up to ₱4.9 million and 5.75% above that, fixed for three years. On a real, move-in-ready Allegra studio that is ₱23,083 a month — about ₱13,321 less than the same unit on a typical bank loan.
Pag-IBIG has its own DMCI payment terms (memo PD-26-10-024): a 12% downpayment over 18 months on ready-for-occupancy units, with no regular 1% discount; the Legacy 20% still applies, and every Pag-IBIG buyer gets ₱10,000 off until December 31, 2026.
For years, whenever a buyer asked me “Can I use my Pag-IBIG for a DMCI unit?” the answer was the same: spot cash, bank or DMCI in-house. Pick one.
That answer just changed. DMCI Homes has made Pag-IBIG financing official on Allegra Garden Place, The Oriana, The Erin Heights, Anissa Heights and twelve more projects on its official list.
It matters because of who it reaches. Every employed Filipino pays into Pag-IBIG, and every OFW has been required to since 2010. Millions of people have years of contributions sitting in the Fund — and until now, none of it could touch a DMCI unit. Below is which units it applies to, what it does to your monthly on real units from DMCI’s October 2026 availability list, and the one Pag-IBIG rule that can quietly cost you about ₱4,000 a month if nobody points it out.
Updated October 21, 2026 · DMCI’s Pag-IBIG payment terms. DMCI memo PD-26-10-024 sets the terms for Pag-IBIG buyers: 12% over 18 months on ready-for-occupancy units, over up to 32 months at The Erin Heights and The Oriana South Tower, 20% until turnover at Anissa Heights. No regular 1% on the 12% term; the Legacy 20% still applies; every Pag-IBIG buyer gets ₱10,000 off until December 31, 2026; closing fees are paid before the loan is released. Every figure below is on those terms.
Which DMCI Projects Accept Pag-IBIG
| Project | Status | Lowest unit open | Pag-IBIG / mo |
|---|---|---|---|
| Allegra Garden Place Pasig Boulevard, Pasig | Ready for occupancy | Studio · ₱5,266,000 | ₱23,083 |
| The Oriana — North Tower Aurora Blvd, Quezon City · 390 m to LRT-2 | Ready for occupancy | 1BR · ₱5,109,000 | ₱22,736 |
| The Oriana — South Tower Same address | Turnover Nov 2027 | Studio · ₱5,222,000 | ₱28,240 at 6.25% |
| The Erin Heights Commonwealth Ave, Quezon City | Turnover Oct 2027 | Studio · ₱5,391,000 | ₱28,718 at 6.25% |
| Anissa Heights P. Zamora St, Pasay · near LRT/MRT Taft | Turnover Jul 2028 | Studio · ₱3,160,500 | ₱15,519 at 6.25% |
The full official list, by city. Most of the projects beyond these four are Legacy Projects. Their 20% Legacy discount (until November 30, 2026) applies with Pag-IBIG too: a Legacy unit is 12% over 18 months with the 20% off, plus ₱10,000. Pag-IBIG applies only to the projects on this list:
Why This Is Big News for OFWs
Pag-IBIG comes off the payslip — usually ₱200 a month, matched by the employer — and for overseas Filipino workers it has been mandatory since Republic Act 9679 took effect in 2010. If you have worked for two years, you very likely already meet the Fund’s requirement of 24 monthly contributions.
- You are already a member. Your contribution record is the relationship — no new lender to win over.
- The monthly is lower — a lower rate and a longer term, which is what you need when you budget a home in pesos on a salary earned abroad.
- You do not need to fly home. A family member here signs for you under a Special Power of Attorney, and I handle the DMCI side of the file.
Pag-IBIG vs Bank: The Same Unit, Side by Side
Two real, available two-bedrooms, each computed both ways. The Pag-IBIG route is on DMCI’s Pag-IBIG terms (memo PD-26-10-024): 12% over 18 months with no regular 1%, plus the ₱10,000 Pag-IBIG special discount — Allegra keeps the Christmas Countdown’s 1.5%. The bank route is on DMCI’s regular terms: 12% over 32 months with the 1%.
| Allegra · Soraya 309 · 2BR, 55 sqm · ₱7,748,000 | Pag-IBIG route | Bank route |
|---|---|---|
| Discount | 1.5% + ₱10,000 Countdown + Pag-IBIG special | 1% + 1.5% regular + Countdown |
| Net price | ₱7,621,780 | ₱7,555,462 |
| 12% downpayment | ₱49,145/mo × 18 | ₱27,395/mo × 32 |
| Balance to finance (88%) | ₱6,707,166 | ₱6,648,807 |
| Loan / month | ₱39,141 5.75% · 30 yrs | ₱53,562 7.5% · 20 yrs |
| Monthly difference | ₱14,421 less | |
| Household income to carry it (≈35%) | ₱111,831 | ₱153,034 |
| The Oriana · North 405 · 2BR, 54.5 sqm · ₱7,501,000 | Pag-IBIG route | Bank route |
|---|---|---|
| Discount | ₱10,000 Pag-IBIG special | 1% |
| Net price | ₱7,491,000 | ₱7,425,990 |
| 12% downpayment | ₱48,273/mo × 18 | ₱26,910/mo × 32 |
| Balance to finance (88%) | ₱6,592,080 | ₱6,534,871 |
| Loan / month | ₱38,470 5.75% · 30 yrs | ₱52,644 7.5% · 20 yrs |
| Monthly difference | ₱14,174 less | |
| Household income to carry it (≈35%) | ₱109,914 | ₱150,411 |
List prices from DMCI’s October 2026 availability list, computed October 21, 2026. Bank shown at an indicative 7.5% fixed over 20 years; your bank sets the actual rate at approval.
Read the last row twice. On the Allegra 2-bedroom the bank route needs roughly ₱153,034 a month in household income; Pag-IBIG needs about ₱111,831. For many families that is the difference between “not yet” and “yes.”
The honest part: the Pag-IBIG route costs something on the way in. On the Allegra 2-bedroom you give up the regular 1% (₱66,318 on the price, after the ₱10,000 special) and pay the downpayment over 18 months instead of 32 — ₱49,145 a month instead of ₱27,395. Some of the monthly gap is also the extra ten years: on the bank’s 20-year term the Pag-IBIG loan is ₱47,090 a month, still ₱6,472 less from the rate alone. And a 30-year loan pays interest for longer: about ₱14,090,760 over 30 years versus ₱12,854,880 over 20. Pag-IBIG wins on the monthly and on qualifying; if you can pay more than the minimum, ask me how to structure it so you also win on the total.
The ₱4.9 Million Line
Pag-IBIG’s two promo rates are split by loan size — 4.5% up to ₱4.9 million, 5.75% above it — on the whole loan. Allegra Amina 919, a 30 sqm one-bedroom at ₱5,710,000, leaves a balance of ₱4,940,628 on DMCI’s Pag-IBIG 12% term: ₱40,628 over the line, so it prices at 5.75% — ₱28,832 a month.
The fix: pay that ₱40,628 as extra downpayment. The loan drops to ₱4,900,000, qualifies for 4.5%, and the monthly falls to ₱24,828 — ₱4,004 a month less, or ₱144,144 over the three-year fixed period. Same story at Cypress Towers (Legacy): Celesta PH10 leaves a ₱4,942,432 balance on the Pag-IBIG route — ₱42,432 over the line — and pulling it under saves ₱4,015 a month. Confirm the bracket on your own loan with Pag-IBIG when you file.
Allegra Garden Place, Pasig
Two finished 55-storey towers, Amina and Soraya, on Pasig Boulevard — 110 m from Rizal Medical Center, 3.3 km from Ortigas Center.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| Soraya 2417 · Studio · 30 sqm | ₱5,266,000 | ₱23,083 4.5% | ₱36,404 |
| Amina 919 · 1BR · 30 sqm | ₱5,710,000 | ₱28,832 5.75% | ₱39,474 |
| Soraya 309 · 2BR · 55 sqm | ₱7,748,000 | ₱39,141 5.75% | ₱53,562 |
Pag-IBIG column on DMCI’s Pag-IBIG terms: 12% over 18 months, Christmas Countdown 1.5% (no regular 1%) plus the ₱10,000 Pag-IBIG special discount. Bank column on the regular terms: 12% over 32 months, 1% + 1.5%, then an indicative 7.5% over 20 years.
The studio is the headline: a finished, move-in-ready Pasig address on a Pag-IBIG loan of ₱23,083 a month. On the Pag-IBIG route its 12% downpayment runs 18 months — ₱32,847 a month — and the Christmas Countdown’s 1.5% (1% in November) is already in these figures.
The Oriana, Quezon City
A 54-storey North Tower on Aurora Boulevard, Project 4 — 390 m to LRT-2, with Anonas, Katipunan and Cubao stations minutes away — is ready for occupancy: Pag-IBIG buyers pay 12% over 18 months. The South Tower turns over in November 2027: 12% over up to 32 months, and its loan is filed later, so it is shown at the regular rate. Neither tower takes a % discount on the Pag-IBIG 12% term; both get the ₱10,000 Pag-IBIG special discount.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| North 1906B · 1BR · 29 sqm | ₱5,109,000 | ₱22,736 4.5% | ₱35,857 |
| North 405 · 2BR · 54.5 sqm | ₱7,501,000 | ₱38,470 5.75% | ₱52,644 |
| South MZ09 · Studio · 30 sqm | ₱5,222,000 | ₱28,240 6.25% | ₱36,650 |
The Legacy Projects: the 20% and Pag-IBIG
DMCI’s Pag-IBIG terms settle the question I was asked most this week: the Legacy 20% discount applies with Pag-IBIG too. With Pag-IBIG financing, a Legacy unit is a 12% downpayment over 18 months with the 20% off (memo PD-26-05-026, until November 30, 2026), plus the ₱10,000 Pag-IBIG special discount until December 31, 2026.
So on a Legacy unit you no longer choose between the lower price and the lower monthly: Pag-IBIG gives you both. Actual units open on DMCI’s October 2026 list:
| Community · unit | List price | Bank route: after 20% | Pag-IBIG route: after 20% + ₱10,000 | Pag-IBIG downpayment |
|---|---|---|---|---|
| Mayfield Park Residences Mandala 213 · 2BR · 42 sqm · Cainta | ₱4,380,000 | ₱3,504,000 ₱24,841/mo bank | ₱3,494,000 ₱15,579/mo · 4.5% | ₱21,627/mo × 18 |
| Raya Garden Condominiums Surabaya 432 · Studio · 31 sqm · Parañaque | ₱4,303,000 | ₱3,442,400 ₱24,404/mo bank | ₱3,432,400 ₱15,304/mo · 4.5% | ₱21,216/mo × 18 |
| Maricielo Villas Almeria 103 · 2BR · 53 sqm · Las Piñas | ₱5,663,000 | ₱4,530,400 ₱32,117/mo bank | ₱4,520,400 ₱20,156/mo · 4.5% | ₱28,469/mo × 18 |
| Alea Residences Budi 304 · 2BR · 55 sqm · Bacoor, Cavite | ₱6,343,000 | ₱5,074,400 ₱35,974/mo bank | ₱5,064,400 ₱22,581/mo · 4.5% | ₱32,096/mo × 18 |
| Rhapsody Residences Viola 302 · 2BR · 55.5 sqm · Muntinlupa | ₱6,855,000 | ₱5,484,000 ₱38,877/mo bank | ₱5,474,000 ₱24,408/mo · 4.5% | ₱34,827/mo × 18 |
| Cypress Towers Celesta PH10 · 2BR · 48 sqm · Taguig (C-5) | ₱7,033,000 | ₱5,626,400 ₱39,887/mo bank | ₱5,616,400 ₱28,843/mo · 5.75% | ₱35,776/mo × 18 |
| East Raya Gardens Banyan 116 · 2BR · 62.5 sqm · Pasig | ₱7,388,000 | ₱5,910,400 ₱41,900/mo bank | ₱5,900,400 ₱30,301/mo · 5.75% | ₱37,669/mo × 18 |
Bank route: 20% Legacy Projects special discount per DMCI memo PD-26-05-026, units only, until November 30, 2026; 12% over 32 months, then an indicative 7.5% bank loan over 20 years. Pag-IBIG route: the same 20%, plus the ₱10,000 Pag-IBIG special discount (until December 31, 2026), 12% over 18 months (DMCI memo PD-26-10-024), Pag-IBIG over 30 years. Other projects on DMCI’s Pag-IBIG list had no open units on the list — they resurface on DMCI’s reopened lists, so ask me.
On the Mayfield Park two-bedroom, Pag-IBIG is ₱10,000 cheaper on the price and ₱15,579 a month against ₱24,841 on the bank loan. What it asks of you is the shorter downpayment: ₱21,627 a month over 18 months instead of ₱12,202 over 32. The 20% ends November 30, so reserve before then either way.
The Erin Heights: Downpayment Now, Pag-IBIG Later
Commonwealth Avenue corner Tandang Sora, 1.1 km from UP Diliman; turnover scheduled for October 2027. You pay the 12% downpayment to DMCI over up to 32 months (DMCI allows 18 to 32) and Pag-IBIG takes out the 88% balance after that. Erin keeps the Christmas Countdown on the Pag-IBIG term — 1.5% off in October, 1% in November — as its only % discount, plus the ₱10,000 Pag-IBIG special discount. Because the loan is filed later, it is shown at 6.25% — not a promo rate that may not exist by then. If Pag-IBIG extends the promo, the monthly only goes down.
| Unit | List price | Downpayment / mo | Pag-IBIG / mo |
|---|---|---|---|
| Erin 3103 · Studio · 28.5 sqm | ₱5,391,000 | ₱18,938 × 32 | ₱28,718 |
| Erin 704 · 2BR · 48.5 sqm | ₱7,434,000 | ₱26,484 × 32 | ₱39,621 |
| Erin 601 · 3BR · 84 sqm | ₱11,264,000 | ₱40,631 × 32 | ₱60,062 |
Anissa Heights, Pasay
P. Zamora Street, Pasay — near the LRT/MRT Taft interchange — with turnover in July 2028. Studios start at ₱3,160,500 for 16 sqm, the lowest DMCI entry price on the current list. On DMCI’s Pag-IBIG terms Anissa takes 20% down, payable until turnover (₱30,005 a month on that studio, after the ₱30,000 reservation), with no % discount but ₱10,000 off; Pag-IBIG then finances the ₱2,520,400 balance — about ₱15,519 a month at the regular 6.25% over 30 years.
Do You Qualify?
- 24 monthly contributions posted — check them on Virtual Pag-IBIG.
- Age: 65 or younger when you apply and 70 or younger when the loan matures.
- Income that carries the monthly — as a working rule, keep it within about 35% of gross household income. Co-borrowers can be combined.
- No foreclosed, cancelled or bought-back Pag-IBIG housing loan in your name.
- Loan within ₱10 million and within Pag-IBIG’s appraisal of the unit.
How to Buy With Pag-IBIG Financing
- Send me your contribution count and budget. I match you to units and compute Pag-IBIG against the bank, including the ₱4.9M line check.
- Reserve with ₱30,000. The unit comes off the market and your price is locked.
- Pay the downpayment on DMCI’s Pag-IBIG schedule. 12% over 18 months at Allegra, The Oriana North Tower and the Legacy Projects; over up to 32 months at The Erin Heights and The Oriana South Tower; 20% until turnover at Anissa Heights.
- File your Pag-IBIG housing loan — early. I prepare the DMCI documents Pag-IBIG asks for; OFWs file through a Special Power of Attorney. Once Pag-IBIG approves, you may finish the downpayment sooner with no restructuring fee.
- Pag-IBIG appraises and approves. It values the unit and issues its approval and guaranty to DMCI.
- Pay the closing fees, then Pag-IBIG releases the loan. Closing fees are not part of the Pag-IBIG loan, so they are settled first. On the release you start paying Pag-IBIG instead of DMCI, and DMCI turns over the unit and any parking bought with it.
Good to know
- Lower monthly and easier to qualify than most bank loans.
- Works with the Christmas Countdown on Allegra and The Erin Heights — 1.5% off in October, 1% in November.
- Keeps the Legacy 20%, plus ₱10,000 off for every Pag-IBIG buyer until December 31, 2026.
- Only on the eligible projects above — not on other DMCI projects or private resales.
Watch out for
- The downpayment runs 18 months on ready units — shorter than the 32-month bank term.
- No regular 1% on the Pag-IBIG 12% term at Allegra, The Erin Heights and The Oriana.
- Closing fees are not in the loan — pay them before release.
- The promo rate is fixed for 3 years, then reprices; Pag-IBIG lends against its own appraisal, which can come in under DMCI’s price.
- The 5% downpayment RFO promo is Chinabank/BPI only.
Questions About Pag-IBIG at DMCI
Does DMCI Homes accept Pag-IBIG financing?
Yes, on specific projects. DMCI Homes accepts Pag-IBIG Fund housing loans for the balance only on the 16 projects on its official Pag-IBIG list (October 2026), including Allegra Garden Place (Pasig), The Oriana and The Erin Heights (Quezon City) and Anissa Heights (Pasay). Its Pag-IBIG payment terms (memo PD-26-10-024): a 12% downpayment over 18 months on ready-for-occupancy projects, over up to 32 months at The Erin Heights and The Oriana South Tower, and 20% until turnover at Anissa Heights. The Legacy 20% still applies with Pag-IBIG, and every Pag-IBIG buyer gets ₱10,000 off until December 31, 2026. On those projects Pag-IBIG sits alongside spot cash, bank financing and DMCI in-house financing. It is not offered on other DMCI projects.
Which DMCI projects can I buy with a Pag-IBIG housing loan?
DMCI's official Pag-IBIG list (October 2026), by city — Cainta: Mayfield Park Residences; Cavite: Alea Residences; Davao: Verdon Parc; Las Piñas: Maricielo Villas; Mandaluyong: Dansalan Gardens Condominiums, Tivoli Garden Residences; Muntinlupa: Rhapsody Residences; Parañaque: Palm Grove Residences, Raya Garden Condominiums; Pasay: Anissa Heights; Pasig: Allegra Garden Place, East Raya Gardens; Quezon City: The Erin Heights, The Oriana; Taguig: Cypress Towers, Rosewood Pointe. At The Oriana it covers both the North and South Towers. Unit availability inside each project changes daily.
How much can Pag-IBIG lend me for a DMCI condo?
Up to ₱10 million per borrower, payable over as long as 30 years — Pag-IBIG raised the ceiling from ₱6 million in May 2026. What you actually get depends on your capacity to pay, your credit evaluation and Pag-IBIG's own appraisal of the unit. If the appraisal comes in below your balance, the difference is paid as additional equity.
What is the Pag-IBIG housing loan interest rate in 2026?
For homes above the socialized-housing ceiling, Pag-IBIG is running promotional rates of 4.5% a year on loans up to ₱4.9 million and 5.75% above ₱4.9 million up to ₱10 million, fixed for the first three years, for applications filed until December 31, 2026. After the fixing period the rate reprices. A loan filed later — for a unit that turns over in 2027 or 2028 — should be planned at Pag-IBIG's regular rate, about 6.25% for a 3-year fix.
Can OFWs use Pag-IBIG to buy a DMCI condo?
Yes, and OFWs are the buyers this helps most. Pag-IBIG membership has been mandatory for overseas Filipino workers since Republic Act 9679, so most OFWs already have years of contributions posted. You can apply from abroad: a family member in the Philippines signs for you under a Special Power of Attorney.
How many Pag-IBIG contributions do I need to apply for a housing loan?
At least 24 monthly contributions. You should also be no older than 65 when you apply and no older than 70 when the loan matures, have no foreclosed or cancelled Pag-IBIG housing loan, and show income that can carry the monthly amortization.
Is Pag-IBIG cheaper than a bank loan for a DMCI unit?
Month to month, almost always. On a 2-bedroom at Allegra Garden Place (Soraya 309), the Pag-IBIG amortization is ₱39,141 a month over 30 years against about ₱53,562 at an indicative 7.5% bank rate over 20 years — ₱14,421 less. The Pag-IBIG route has a shorter 18-month downpayment and no regular 1% discount, and part of the monthly gap is the longer term: over the full life of the loan, 30 years pays more total interest than 20, so if you can pay more than the minimum, structure it that way.
How much downpayment do I need for a DMCI unit with Pag-IBIG financing?
12% on every project on DMCI's Pag-IBIG list except Anissa Heights, which takes 20%. Under memo PD-26-10-024 the 12% runs over 18 months on ready-for-occupancy projects and over up to 32 months at The Erin Heights and The Oriana South Tower; Anissa Heights' 20% runs until turnover. The ₱30,000 reservation fee comes off the downpayment, and Pag-IBIG finances the balance. Every Pag-IBIG buyer also gets a ₱10,000 Pag-IBIG special discount until December 31, 2026. The 5% downpayment move-in promo for ready-for-occupancy units is tied to Chinabank or BPI financing, so it is not the route for a Pag-IBIG buyer.
Can I combine the Legacy Projects 20% discount with Pag-IBIG financing?
Yes. Under DMCI's Pag-IBIG terms (memo PD-26-10-024), a Legacy Project unit bought with Pag-IBIG financing keeps the Legacy Projects 20% special discount (memo PD-26-05-026, until November 30, 2026) on a 12% downpayment over 18 months, plus a ₱10,000 Pag-IBIG special discount until December 31, 2026. The Legacy Projects on DMCI's Pag-IBIG list are Alea, Cypress Towers, East Raya Gardens, Maricielo Villas, Mayfield Park, Raya Garden, Rhapsody, Rosewood Pointe and Tivoli Garden.
Can I use Pag-IBIG on a pre-selling DMCI unit?
On the eligible pre-selling projects, yes — The Erin Heights (turnover October 2027), The Oriana South Tower (November 2027) and Anissa Heights (July 2028). You pay the downpayment to DMCI first (12% over up to 32 months at Erin and Oriana South, 20% until turnover at Anissa) and Pag-IBIG takes out the balance later, so plan at the regular rate: an Erin Heights studio (Erin 3103) is about ₱28,718 a month at 6.25% over 30 years.
Are closing fees included in the Pag-IBIG loan at DMCI?
No. DMCI's Pag-IBIG terms (memo PD-26-10-024) leave the closing fees out of the loan amount: you pay them before Pag-IBIG releases the loan, at DMCI's regular rates. The unit and any parking bought with it are turned over when Pag-IBIG releases the loan.
Sources
- DMCI Pag-IBIG payment terms — DMCI Homes interoffice memorandum PD-26-10-024, “Pag-IBIG Financing Standard Payment Terms”, October 16, 2026
- Pag-IBIG Fund raises limit on housing loans to ₱10 million — Philstar, May 29, 2026
- 4.5% promotional rate on loans up to ₱4.9 million; 5.75% above, up to ₱10 million — Daily Tribune, July 8, 2026
- Promo rates valid until December 31, 2026 — Daily Tribune, October 2026
- Mandatory Pag-IBIG membership for overseas Filipino workers — Republic Act No. 9679 (Home Development Mutual Fund Law of 2009)
- Unit prices and availability — DMCI Homes availability list, October 2026 (recomputed October 21, 2026); Legacy discount per DMCI memo PD-26-05-026; Christmas Countdown per DMCI memo PD-26-09-031
Send me your contribution count
Tell me how many months of Pag-IBIG you have and the project you like. I will send back the real unit, the Pag-IBIG route against the bank route, and whether you are on the right side of the ₱4.9M line.
💬 WhatsApp Jeffrey 🧮 Compute a unit